Mixed-Use Rural Estate Finance: Funding Businesses with Multiple Properties and Income…
Farm Succession: Planning the Finance as Well as the Tax
Farm Succession: Planning the Finance as Well as the Tax
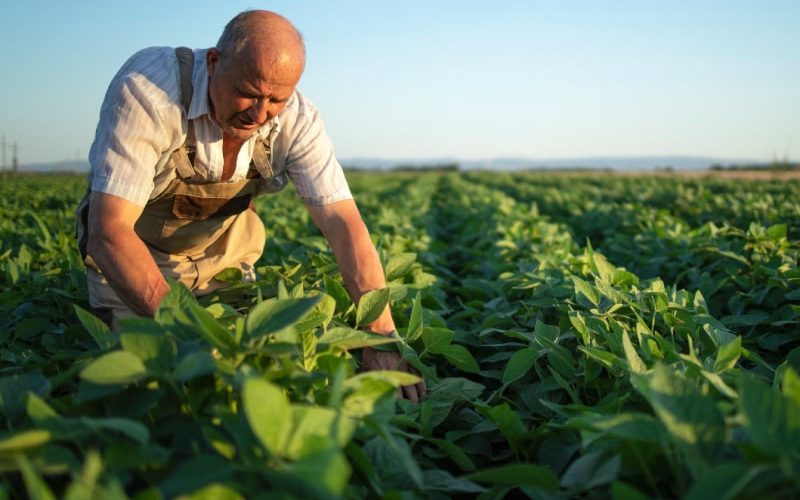
Farm succession planning has always involved more than deciding who will inherit the land. Families must also consider who will operate the business, how assets will be divided, what will happen to existing borrowing and whether the next generation will have enough capital to take the farm forward.
Changes to Agricultural Property Relief and Business Property Relief, which took effect on 6 April 2026, have given many farming families another reason to review those plans.
The combined value of qualifying agricultural and business property that can receive 100% relief is now limited to £2.5 million. Qualifying value above the available allowance generally receives relief at 50%. Any unused allowance may be transferred between spouses or civil partners, potentially providing a combined allowance of up to £5 million, subject to the individual circumstances and applicable rules.
Although government forecasts indicate that most estates claiming Agricultural Property Relief will not pay more Inheritance Tax as a result of the reforms, the changes have highlighted the importance of understanding how a farm would transfer in practice.
Professional tax and legal advice is essential. However, a technically sound succession plan must also be financially workable.
Farm Succession Is Not Just a Tax Calculation
Inheritance Tax may be one part of the conversation, but succession raises much broader commercial and personal questions.
These can include:
- Who will own the land and agricultural buildings?
- Who will operate the farming business?
- Will ownership and management pass to the same person?
- How will children who do not work on the farm be treated?
- Are there diversified enterprises, residential properties or commercial assets to consider?
- What existing mortgages, loans or secured liabilities will remain?
- Will the successor have enough working capital?
- Could the proposed division of assets leave the farm commercially unviable?
These decisions are closely connected. A solution that appears fair when measured by asset value may not create a farming business capable of supporting the next generation.
For example, dividing land between several beneficiaries may provide each person with an asset, but it could reduce the scale or security of the farming enterprise. Passing the entire farm to one successor may preserve the business but create a need to provide capital or other assets to siblings.
The family therefore needs to consider both inheritance and long-term business viability.
Establish What the Farm and Estate Include
Before deciding how a rural estate should transfer, it is helpful to establish exactly what is owned, how it is used and where liabilities sit.
The complete picture might include:
- Agricultural land
- Farmhouses and cottages
- Agricultural buildings
- Machinery and livestock
- Partnership or company interests
- Diversified rural businesses
- Renewable energy projects
- Commercial units
- Holiday accommodation
- Investment property
- Existing debts and guarantees
- Tenancies, leases and occupation arrangements
It is also important not to assume that every part of a rural estate will automatically receive the same tax treatment.
Agricultural Property Relief relates to the agricultural value of qualifying property. For example, any value attached to a farmhouse above its agricultural value, such as an additional country-residence value, may not qualify for Agricultural Property Relief. Business Property Relief may apply to some assets not fully covered by Agricultural Property Relief where the relevant conditions are met.
The family’s solicitor, accountant and specialist tax adviser should determine which assets and reliefs apply. The finance discussion can then be based on a much clearer understanding of the estate.
Financing a Buyout Between Family Members
One of the most common succession challenges arises when one family member wants to continue farming while others do not.
The farming successor may inherit or acquire the operational business but need to provide value to siblings or other beneficiaries. Where there is insufficient cash or suitable non-farming property elsewhere in the estate, a buyout may need to be considered.
Borrowing secured against agricultural land or property could potentially provide the capital needed to complete that arrangement while keeping the farm together.
However, the level and structure of borrowing must remain affordable for the agricultural business.
The assessment should consider:
- The farm’s historic and projected profitability
- Agricultural and diversified income
- Existing debts
- The proposed payment to other beneficiaries
- The security available
- The successor’s experience and business plan
- Future investment requirements
- The effect of interest and repayments on farm cashflow
The objective should not simply be to complete the transfer. It should be to leave the successor with a viable business afterwards.
Refinancing Existing Agricultural Borrowing
Succession can also be an appropriate point to review existing borrowing.
A farm may have several facilities accumulated over many years, including mortgages, equipment finance, overdrafts, private loans or short-term borrowing. Some may be secured against different parts of the estate or supported by personal guarantees from the retiring generation.
Those arrangements may not transfer neatly to the new owner or business structure.
Refinancing could potentially:
- Consolidate several liabilities
- Replace borrowing that is no longer suitable
- release a retiring family member from an existing arrangement
- Align repayments more closely with agricultural cashflow
- Create a clearer financial position before or during the transfer
- Provide additional capital for an agreed family settlement
Any refinancing decision should account for fees, early repayment charges, the total cost of the new borrowing and the longer-term effect on the business.
Creating Liquidity Without an Immediate Land Sale
Where an estate faces an Inheritance Tax liability or needs to provide funds to several beneficiaries, the first assumption may be that land or property will need to be sold.
In some cases, selling a non-core asset may be the most appropriate solution. However, an unplanned or urgent sale could reduce the farm’s productive capacity, remove security from the business or produce a poorer result than a properly marketed disposal.
The April 2026 reforms extended the option to pay Inheritance Tax in equal annual instalments over ten years, interest-free, to all property eligible for Agricultural Property Relief or Business Property Relief.
That option does not remove the liability, and professional advice is required to understand how it applies. It may nevertheless form part of a wider liquidity plan.
Depending on the circumstances, finance could also provide time to:
- Market an asset properly rather than arranging a forced sale
- Continue operating the farm while longer-term decisions are made
- Complete a family buyout
- Reorganise existing borrowing
- Invest in changes needed to make the successor’s business sustainable
Borrowing should not be used to postpone an unavoidable problem indefinitely. It should support a credible plan with a clear and realistic repayment strategy.
Consider a Staged Farm Transfer
Succession does not always need to happen in a single transaction.
A staged approach may allow the next generation to take on greater management responsibility while the current owners remain involved. Ownership of the operating business, machinery, livestock and property may also transfer at different points, subject to professional legal and tax advice.
A staged plan can help families:
- Test whether the proposed successor is ready
- Preserve knowledge and relationships
- Introduce financial responsibility gradually
- Build evidence of the successor’s ability to operate the business
- Complete necessary refinancing or investment in advance
- Avoid rushed decisions during illness or bereavement
The potential tax consequences of gifts, transfers, partnerships, companies and trusts can be complex. Families should therefore agree the intended commercial outcome before asking advisers to help create the appropriate structure.
Give the Successor Enough Capital to Operate
A succession plan can transfer valuable land while leaving the next generation without enough cash to farm it effectively.
The new operator may need working capital for:
- Seed, feed and fertiliser
- Livestock purchases
- Machinery repairs or replacement
- Labour and contractors
- Rent and finance payments
- Building improvements
- Compliance and environmental work
- Diversification or efficiency investment
If the successor begins with substantial borrowing but little working capital, even a profitable farm may experience immediate pressure.
The financial plan should therefore cover both the transfer and the first years of operation. This may mean retaining cash within the business, arranging suitable working-capital facilities or phasing payments to family members where all parties and their advisers agree.
Bring the Right Advisers Together Early
Effective farm succession usually requires input from several professionals, including:
- A solicitor
- An accountant
- A specialist tax adviser
- A valuer or land agent
- The family’s existing bank or lender
- An agricultural finance specialist
Each adviser has a different role. The tax adviser can explain the applicable reliefs and liabilities, while the solicitor can document the agreed ownership and business structure.
A finance provider must understand whether the resulting plan is affordable and how any proposed borrowing will be repaid.
Beginning those discussions early gives the family more choices. Waiting until a death, health crisis or fixed deadline can limit the available options and make an already emotional process considerably more difficult.
Bespoke Finance for Farm Succession
UK Agricultural Finance does not provide legal, tax or estate-planning advice. We work alongside the borrower’s professional advisers to understand the funding requirement created by an agreed succession plan.
Depending on the circumstances, finance secured against agricultural land or property may help fund a family buyout, restructure existing liabilities, support a staged transfer or provide capital for the successor’s wider business plan.
Sue McIntosh-Gibbs has more than 35 years of experience in finance and comes from a farming background. Her experience across agriculture and financial services enables her to understand the needs of borrowers ranging from smallholdings to larger country estates.
The 2026 Inheritance Tax changes may have prompted families to revisit succession, but the strongest plan will consider much more than the tax position. It should protect relationships where possible, preserve a viable rural business and ensure the next generation has the financial foundation needed to move forward.
To discuss finance connected with agricultural succession, generational transfer or estate restructuring, contact Sue on 07549 709 031 or email suemg@ukagriculturalfinance.com.

Related Posts